
Sound Money Project
-

•
Inflation Picked Up in January, Latest BEA Data Show
The Core PCE Price Index increased at an annualized rate of 3.5% in January 2025, rising from 2.5% in the previous month.
-

•
‘Audit the Fed’: Meaning and Risks
The real risk in passing an “Audit the Fed” bill lies in the high likelihood of politicizing monetary policy even more.
-

•
Powell’s Revisionist History of Inflation Targeting
Inflation wasn’t transitory, and neither is the blame for it. Powell’s attempt to rewrite history just doesn’t match the data.
-

•
December Inflation Meets Expectations
Headline inflation rates will almost certainly decline in the coming months, as seasonal distortions fade and monetary policy remains tight.
-

•
The Fed Pushes Pause
Fed officials have delayed adjusting the federal funds rate, perhaps believing that the neutral rate of interest has risen.
-
•
Against Central Bank Independence
Central banks should be apolitical, not unaccountable. Monetary technocrats should serve the People.
-
•
To Whip Inflation, Trump Needs The Courage To Be Unpopular
When the President and Congress blow out the budget, the difference is borrowed from future (imagined) surpluses. That depreciates the dollar.
-
•
Forecasts Stable: The Fed Should Take a Breather
Monetary policy is right where we want it: close to neutral. No cuts are needed as price pressures continue to moderate.
-
•
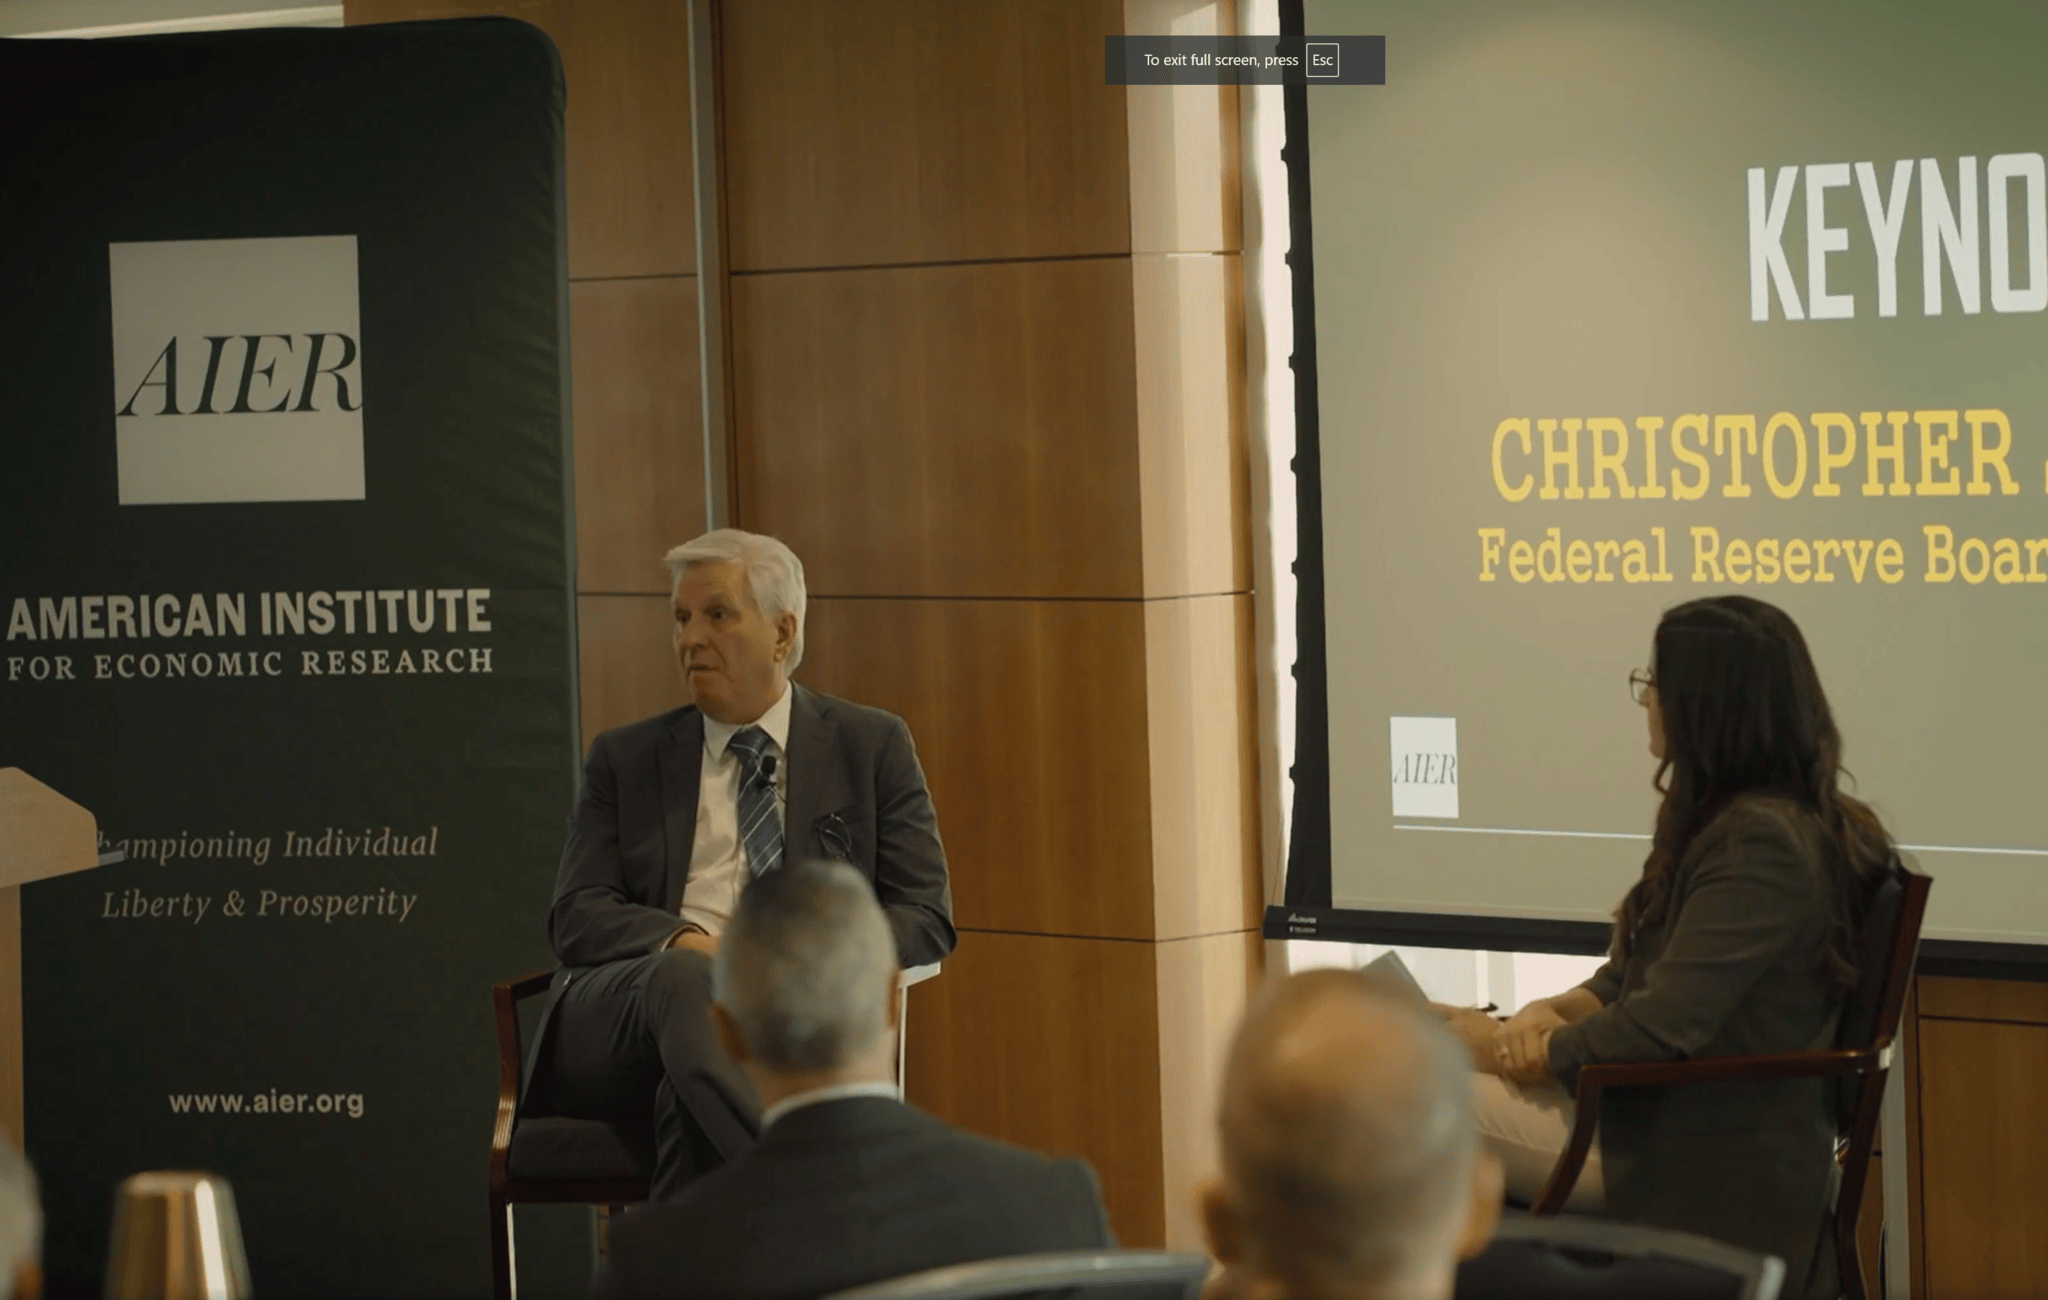
What Happened at the 2024 AIER Monetary Conference: Building a Better Fed Framework?
A jam-packed day of monetary history, theory, policy, and their real-world effects. Watch the video for free today!
-

•
The FOMC Should Hold Rates Steady
Monetary policy remains tight. We have enough data to see a (hopefully temporary) stall in disinflation. FOMC should keep its target rate at 4.50 to 4.75 percent for now.
-
•
Inflation Picked Up in January, Latest BEA Data Show
The Core PCE Price Index increased at an annualized rate of 3.5% in January 2025, rising from 2.5% in the previous month.
-
•
‘Audit the Fed’: Meaning and Risks
The real risk in passing an “Audit the Fed” bill lies in the high likelihood of politicizing monetary policy even more.
-
•
Powell’s Revisionist History of Inflation Targeting
Inflation wasn’t transitory, and neither is the blame for it. Powell’s attempt to rewrite history just doesn’t match the data.
-
•
December Inflation Meets Expectations
Headline inflation rates will almost certainly decline in the coming months, as seasonal distortions fade and monetary policy remains tight.
-
•
The Fed Pushes Pause
Fed officials have delayed adjusting the federal funds rate, perhaps believing that the neutral rate of interest has risen.
-
•
Against Central Bank Independence
Central banks should be apolitical, not unaccountable. Monetary technocrats should serve the People.
-
•
To Whip Inflation, Trump Needs The Courage To Be Unpopular
When the President and Congress blow out the budget, the difference is borrowed from future (imagined) surpluses. That depreciates the dollar.
-
•
Forecasts Stable: The Fed Should Take a Breather
Monetary policy is right where we want it: close to neutral. No cuts are needed as price pressures continue to moderate.
-
•
What Happened at the 2024 AIER Monetary Conference: Building a Better Fed Framework?
A jam-packed day of monetary history, theory, policy, and their real-world effects. Watch the video for free today!
-
•
The FOMC Should Hold Rates Steady
Monetary policy remains tight. We have enough data to see a (hopefully temporary) stall in disinflation. FOMC should keep its target rate at 4.50 to 4.75 percent for now.